You’re making million-euro decisions based on spreadsheets

Every serious financial decision your organisation makes gets put through the wringer. Budgets are audited. Forecasts get challenged in the room. Investment proposals don’t get past the board without evidence behind them.

Energy plays by different rules.

Most organisations are still running their energy decisions through spreadsheets, exports from three different systems, and assumptions that have quietly built up over several years. The numbers look precise. Precise and accurate are not the same thing.

There’s nothing wrong with a spreadsheet, by the way. The problem is that a spreadsheet can’t tell you whether the information inside it actually reflects what’s happening in the building.

A spreadsheet can’t stand up in front of a board and defend a €5 million investment

When an organisation decides to install a heat pump, increase electrical capacity, or commit millions to energy infrastructure, the decision usually starts life as a spreadsheet that has never once been verified.

Almost nobody stops to ask the obvious question: could we actually defend these numbers if someone pushed back? If the honest answer is no, everything calculated from that point on is questionable.

A spreadsheet can be formatted beautifully and still lead an organisation to the wrong decision.

This is where assumptions get expensive

This is the moment organisations expose themselves to risk they didn’t need to take. Infrastructure gets sized for demand nobody measured. Business cases lean on information that’s incomplete. Capital gets committed before anyone has worked out what the building actually requires.

That’s not really a data problem. It’s a governance problem.

Finance has auditing, reconciliation, accountability, and controls built in as standard. Energy, too often, has a spreadsheet that gets emailed between departments.

That gap is worth taking seriously.

Evidence changes the decision

At Dublin Airport, measured operational demand came in significantly lower than the assumptions that had been driving infrastructure planning. That single change led to a fundamentally different investment decision — avoiding infrastructure the airport never needed and reducing the capital required. None of that would have been possible without replacing assumption with measurement.

Spreadsheets are a fine way to support a decision.

They should never be the evidence behind it.
Read more >

What is energy accounting?

Most organisations would never approve a major financial investment using numbers that cannot be explained, challenged or traced back to their source.

Yet this happens every day with energy.

Buildings are redesigned. Heat pumps are oversized. Grid upgrades are approved. Decarbonisation programmes are funded. All because assumptions gradually become accepted as fact. Nobody asks where the numbers came from. Nobody checks whether they are still true.

Energy Accounting exists to change that.

It applies the same discipline to energy that organisations already expect from finance. Every measurement has a source. Every assumption is visible. Every baseline is justified. Every forecast is tested against reality.

The result isn't better reporting.
It's better decisions.

Energy deserves the same discipline as finance

Financial accounting isn't valuable because it produces reports. It's valuable because people trust the information behind them.

Energy deserves the same discipline.

Too many major energy investments begin before organisations have properly established the problem they're trying to solve. Decisions are made using assumptions that cannot be explained, challenged or verified.

Energy Accounting changes that.

It ensures investment decisions begin with what an organisation can prove, not what it assumes.

From reporting to accountability

For years, energy management has focused on reporting what happened. Energy Accounting asks a different question: can you explain it?

Can you show how demand was established? Can you separate what was measured from what was estimated? Can you explain why the forecast was wrong? Can you demonstrate that an investment delivered the improvement it promised?

If the answer is no, the problem isn't the report. The problem is the information supporting the decision.

Energy Accounting creates a continuous management discipline that measures performance, challenges assumptions, explains variance and verifies outcomes. It turns energy from something organisations report into something they manage.

The next evolution of management

Every critical business function has evolved. Finance evolved into financial management. Quality evolved into quality management. Health and safety evolved into risk management.

Energy is following the same path.

It is no longer simply an operational cost or a sustainability metric. It influences investment, resilience, competitiveness and long-term business performance. Organisations now need the same discipline for energy that they already expect from finance.

That discipline is Energy Accounting.

Read more >

Why organisations keep solving the wrong energy problem

Most energy strategies start with a solution already in mind. A heat pump. More electrical capacity. Solar. A retrofit programme. The conversation quickly becomes about what to install, where to invest and how much it will cost. But there is a more basic question that often gets skipped: do we understand the energy problem well enough to know what we are actually solving? 

The real problem is simpler, and harder to admit

Nobody is fully confident the numbers behind these decisions are right.

And once that confidence is missing, every conversation about energy turns into an argument about assumptions instead of a discussion about facts.

Should we upgrade the electrical capacity? Could this building actually take a heat pump? Which site goes first? Did the last project even deliver what it promised?

None of these questions can be answered with a straight face if nobody can stand behind the data they’re based on.

Technology gets picked before the problem is understood

This is the trap most organisations fall into. They jump straight to selecting the technology — the heat pump, the battery, the bigger grid connection — before they’ve properly established what the building needs in the first place.

The consequences show up later, but they’re predictable. Projects get prioritised in the wrong order. Budget goes to the wrong sites first. Infrastructure gets sized for what someone assumed, not what was actually measured.

It’s not a technology problem. It’s a governance problem.

The honest answer is that the technology was never really the issue. Governance is.

Finance worked this out decades ago. Numbers get audited. Figures get reconciled. Nothing of consequence gets signed off without evidence behind it.

Energy has never been held to the same standard. It’s reported, certainly — but reported and verified are not the same thing.

Until that changes, organisations will keep investing with total confidence in solutions to problems they were never sure they actually had.

Read more >

Poor energy data is exposing organisations to financial and compliance risk

Energy data used to sit in the background, collected and reviewed occasionally, with little impact beyond operational decisions. That is no longer the case.

Today, energy data feeds directly into financial reporting, compliance, and sustainability reporting, which is viewed as key risk factor for investors

Reporting expectations have changed

Across Europe, frameworks like the Corporate Sustainability Reporting Directive (CSRD) are raising the standard for how organisations report on energy use and performance. This is no longer about high-level estimates, it requires consistent, verifiable data that can stand up to scrutiny alongside financial disclosures.

As expectations increase, the gap between what organisations report and what they can actually evidence is becoming more visible.

The problem is not data, it is structure

Most organisations already collect large volumes of energy data, but it is often spread across systems, inconsistent in format, and manually compiled. As a result, it lacks the structure needed to support reliable reporting, auditability, or confident decision-making.

This creates a fundamental issue, because without clear baselines and consistent tracking over time, it becomes difficult to explain what is happening, why it is happening, and whether performance is improving.

Why this becomes a financial risk

When energy data feeds into sustainability disclosures, it directly affects compliance, investor confidence, and audit outcomes. Regulators are already highlighting the risks of inconsistent ESG reporting, particularly where claims cannot be backed by robust data.

If the underlying data is unclear, the conclusions drawn from it become questionable, and that weakens the credibility of the organisation as a whole.

From reporting to accountability

Energy data is no longer a technical output, it is part of financial governance. Leadership teams are expected to understand it, challenge it, and rely on it when making decisions.

That shift changes the requirement completely. It is no longer enough to report data, it needs to be structured, traceable, and defensible.

The real risk is credibility

Most organisations will meet reporting requirements in some form, but the real test is whether they can stand behind the numbers. If energy data cannot be clearly explained or verified, it becomes a liability, not because of what it shows, but because of the uncertainty it creates.

Read more >

Want investment? Be prepared to prove your energy performance

There was a time when sustainability reporting was largely about demonstrating good intentions.

That time is ending.

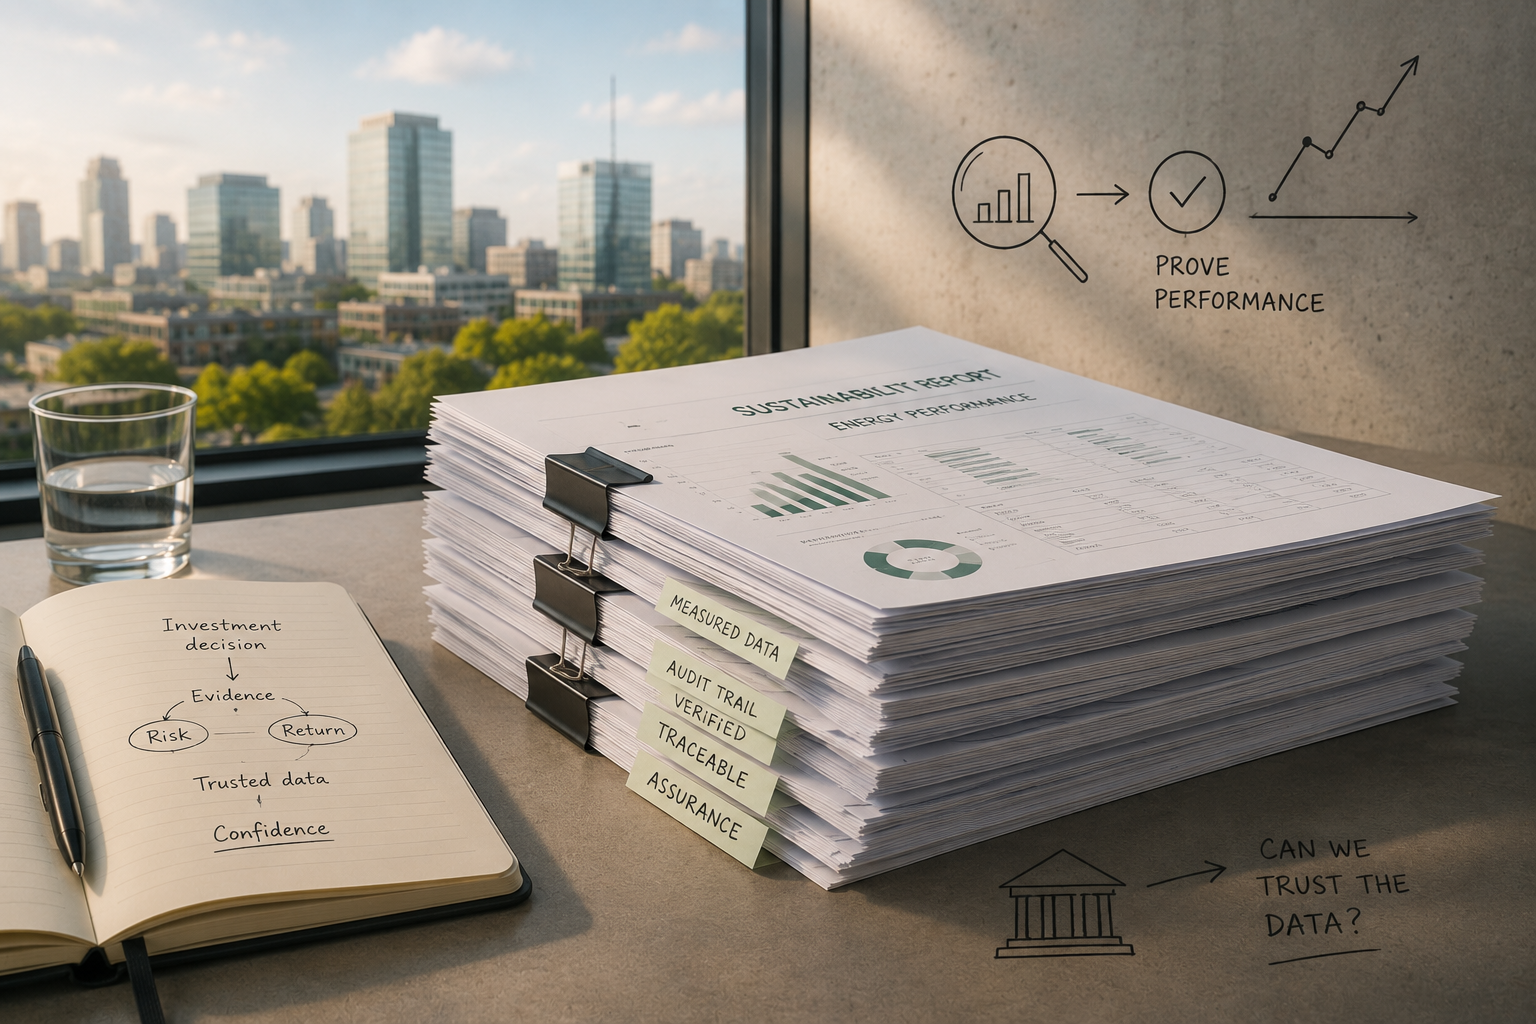
Today, some of Europe's largest investors, lenders, auditors, and regulators are asking tougher questions. They want evidence. They want consistency. Most importantly, they want to understand whether the numbers they are being shown can be trusted.

Sustainability is becoming a due diligence issue

The introduction of CSRD is accelerating a shift that was already underway.

Sustainability information is becoming more standardised, more transparent, and more closely examined. Companies are increasingly expected to produce information that can withstand external assurance, much like financial reporting.

This changes the conversation.

It is no longer enough to say energy consumption has improved. You need to show how you measured it, where the data came from, and whether someone else could verify the result.

Why energy data matters

For many organisations, energy sits at the centre of operational risk, carbon reduction plans, and future investment decisions. Investors understand this.

Energy performance influences operating costs. It affects exposure to future regulation. It impacts carbon reporting. It can even influence the credibility of wider sustainability commitments.

As a result, organisations are increasingly being asked to provide evidence rather than estimates. Not because investors suddenly care about meter readings. Because they care about risk.

Auditors are changing expectations

The major accounting firms are investing heavily in sustainability assurance services. At the same time, regulators are making it clear that sustainability information must become more reliable, consistent, and auditable.

Research from IMD examining some of the first CSRD reports found that organisations are being held to a more consistent standard, making sustainability disclosures easier to compare and scrutinise. As a result, sustainability reporting is moving out of the communications function and into the boardroom.

The Dutch Authority for the Financial Markets (AFM) has explicitly stated that CSRD assurance exists to support reliable and consistent sustainability reporting so investors can make informed decisions. 

Boards, audit committees, investors, and lenders are all asking variations of the same question. Can we trust the data?

From reporting to proof

This is why energy reporting is evolving into something much closer to energy accounting.

Not simply recording consumption, but creating a structured, traceable, and auditable record of performance. The organisations that will be best positioned for future investment will not necessarily be those making the biggest promises.

They will be the organisations that can prove what is actually happening. Because increasingly, investors are asking the same question as auditors.

"Can you show me the evidence?"

Read more >

The most expensive energy project is the one you never needed

When people talk about expensive energy projects, they usually mean the ones that ran over budget, or the ones that didn’t deliver the savings promised on the slide deck.

There’s a bigger cost that almost never gets discussed: the infrastructure that should never have been built at all.

The mistake happens long before anyone signs a contract

Right across Europe, organisations are pouring millions into bigger electrical connections, oversized heat pumps, extra plant, and energy upgrades because they believe their buildings need it.

Often, they don’t.

It usually starts innocently enough. A historic design calculation here. A consultant’s estimate there. A generic demand profile borrowed from a similar building. A few gaps in the operational data, filled in with best guesses.

None of these decisions feel reckless in the moment. Each one looks reasonable on its own. Stack them together, though, and you get a business case that sails through the boardroom — built almost entirely on assumption.

By the time anyone finds out, the money is already spent

It’s usually much later that the real operational demand turns out to be a fraction of what was planned for. By then, the capital is already committed. There’s no getting it back.

This is exactly why better technology was never going to fix this. Better evidence is what fixes it.

Measure first. Invest second.

At Dublin Airport, actual operational measurements showed demand was significantly lower than the figures used during planning. That single piece of evidence changed the infrastructure specification before any money was committed, and avoided capital expenditure the organisation never needed to spend.

The cheapest project isn’t always the smartest investment.

Sometimes the smartest investment is the project you never have to build.

Read more >