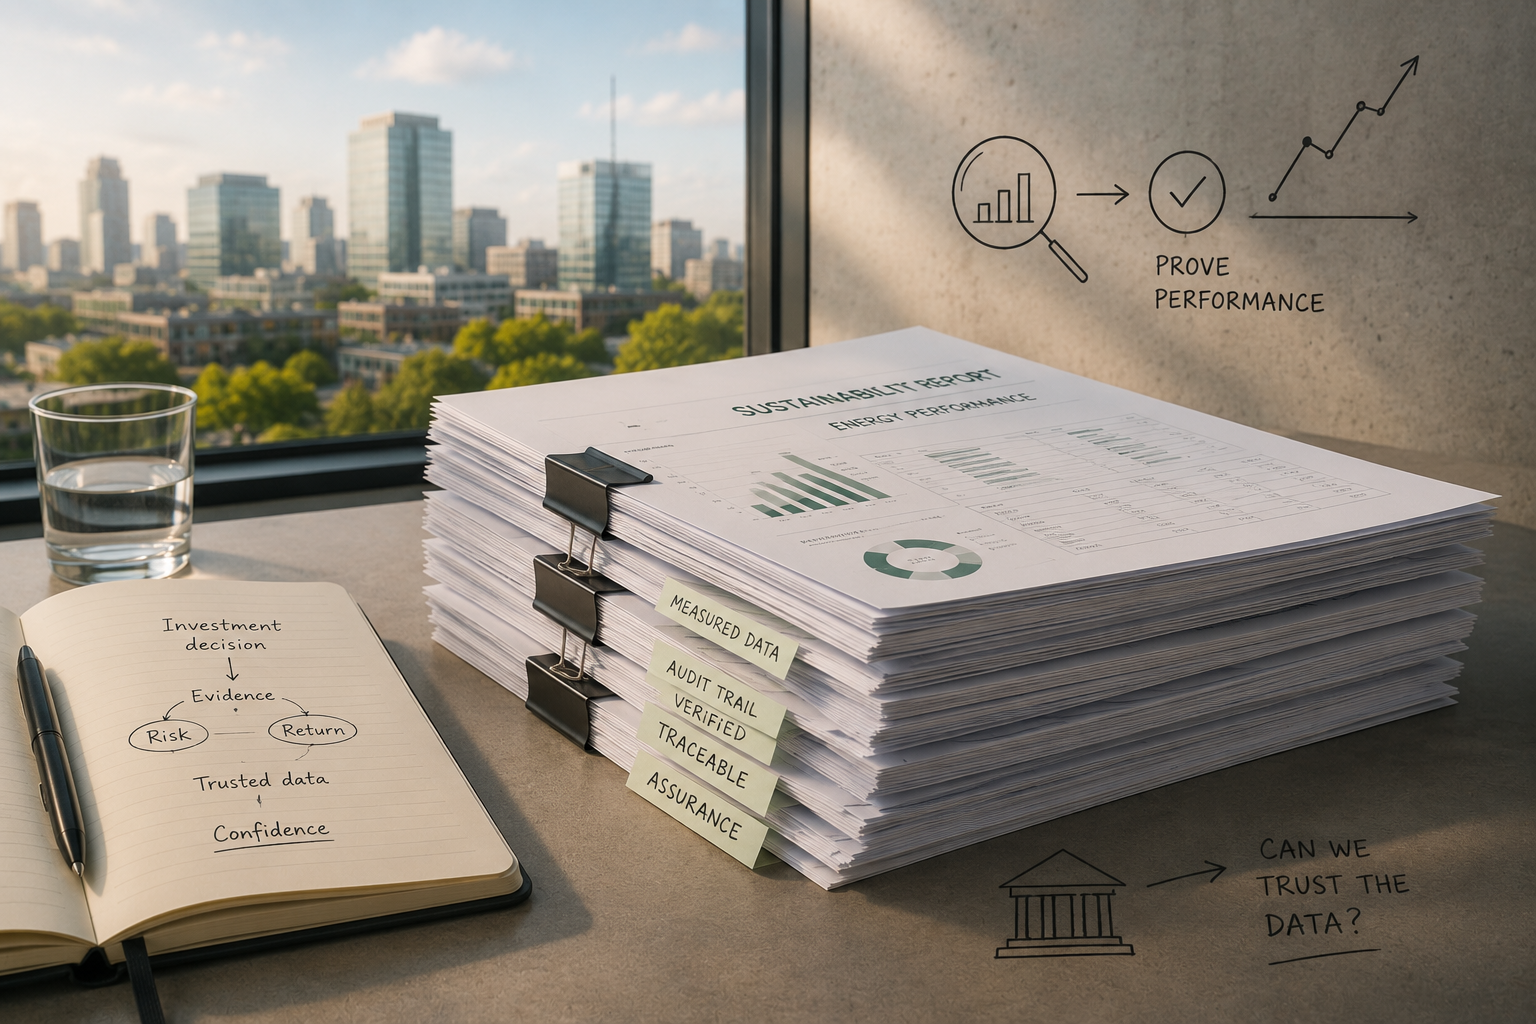
Can you stand behind your sustainability reporting? 

CSRD reporting requirements have brought renewed attention to the quality of sustainability data. But the real issue goes far beyond reporting.

Every year, organisations make significant decisions based on energy information.

Should you invest in a larger electrical connection, or is your existing capacity sufficient? Has a €500,000 energy efficiency project delivered the expected savings? Which building should receive investment first? Is a heat pump being sized using measured demand, or assumptions?

These decisions are only as good as the data behind them.

Who needs to report?

CSRD reporting has already started for the largest public-interest companies. Following the EU's 2026 Omnibus simplification package, mandatory reporting now applies mainly to companies with more than 1,000 employees and more than €450 million in annual turnover.

Many organisations outside the legislation will still be asked to provide sustainability information by customers, investors, lenders, insurers, or supply chain partners.

Whether reporting is mandatory or voluntary, the expectation is increasingly the same. Organisations must be able to explain where their data came from and demonstrate that it is reliable.

Reporting is only as good as the data behind it

Producing a sustainability report is one thing. Being able to validate every figure is another.

Where did the data originate? How was energy consumption calculated? Can reported savings be independently verified? Would someone else analysing the same information reach the same conclusion?

If you can't answer those questions, you can't stand behind your sustainability report. 

Why energy accounting matters

Energy accounting provides a structured, traceable and auditable record of energy performance.

Instead of relying on assumptions, disconnected spreadsheets or manual calculations, organisations can demonstrate where every insight originated and why investment decisions were made.

That supports sustainability reporting, but it also strengthens capital planning, infrastructure investment, operational decision making and long term risk management.

Because the real question isn’t whether you can produce a sustainability report.
It's whether you can stand behind the data that informs every major energy decision.
Read more >

You’re making million-euro decisions based on spreadsheets

Every serious financial decision your organisation makes gets put through the wringer. Budgets are audited. Forecasts get challenged in the room. Investment proposals don’t get past the board without evidence behind them.

Energy plays by different rules.

Most organisations are still running their energy decisions through spreadsheets, exports from three different systems, and assumptions that have quietly built up over several years. The numbers look precise. Precise and accurate are not the same thing.

There’s nothing wrong with a spreadsheet, by the way. The problem is that a spreadsheet can’t tell you whether the information inside it actually reflects what’s happening in the building.

A spreadsheet can’t stand up in front of a board and defend a €5 million investment

When an organisation decides to install a heat pump, increase electrical capacity, or commit millions to energy infrastructure, the decision usually starts life as a spreadsheet that has never once been verified.

Almost nobody stops to ask the obvious question: could we actually defend these numbers if someone pushed back? If the honest answer is no, everything calculated from that point on is questionable.

A spreadsheet can be formatted beautifully and still lead an organisation to the wrong decision.

This is where assumptions get expensive

This is the moment organisations expose themselves to risk they didn’t need to take. Infrastructure gets sized for demand nobody measured. Business cases lean on information that’s incomplete. Capital gets committed before anyone has worked out what the building actually requires.

That’s not really a data problem. It’s a governance problem.

Finance has auditing, reconciliation, accountability, and controls built in as standard. Energy, too often, has a spreadsheet that gets emailed between departments.

That gap is worth taking seriously.

Evidence changes the decision

At Dublin Airport, measured operational demand came in significantly lower than the assumptions that had been driving infrastructure planning. That single change led to a fundamentally different investment decision — avoiding infrastructure the airport never needed and reducing the capital required. None of that would have been possible without replacing assumption with measurement.

Spreadsheets are a fine way to support a decision.

They should never be the evidence behind it.

Read more >

Poor energy data is exposing organisations to financial and compliance risk

Energy data used to sit in the background, collected and reviewed occasionally, with little impact beyond operational decisions. That is no longer the case.

Today, energy data feeds directly into financial reporting, compliance, and sustainability reporting, which is viewed as key risk factor for investors

Reporting expectations have changed

Across Europe, frameworks like the Corporate Sustainability Reporting Directive (CSRD) are raising the standard for how organisations report on energy use and performance. This is no longer about high-level estimates, it requires consistent, verifiable data that can stand up to scrutiny alongside financial disclosures.

As expectations increase, the gap between what organisations report and what they can actually evidence is becoming more visible.

The problem is not data, it is structure

Most organisations already collect large volumes of energy data, but it is often spread across systems, inconsistent in format, and manually compiled. As a result, it lacks the structure needed to support reliable reporting, auditability, or confident decision-making.

This creates a fundamental issue, because without clear baselines and consistent tracking over time, it becomes difficult to explain what is happening, why it is happening, and whether performance is improving.

Why this becomes a financial risk

When energy data feeds into sustainability disclosures, it directly affects compliance, investor confidence, and audit outcomes. Regulators are already highlighting the risks of inconsistent ESG reporting, particularly where claims cannot be backed by robust data.

If the underlying data is unclear, the conclusions drawn from it become questionable, and that weakens the credibility of the organisation as a whole.

From reporting to accountability

Energy data is no longer a technical output, it is part of financial governance. Leadership teams are expected to understand it, challenge it, and rely on it when making decisions.

That shift changes the requirement completely. It is no longer enough to report data, it needs to be structured, traceable, and defensible.

The real risk is credibility

Most organisations will meet reporting requirements in some form, but the real test is whether they can stand behind the numbers. If energy data cannot be clearly explained or verified, it becomes a liability, not because of what it shows, but because of the uncertainty it creates.

Read more >

Want investment? Be prepared to prove your energy performance

There was a time when sustainability reporting was largely about demonstrating good intentions.

That time is ending.

Today, some of Europe's largest investors, lenders, auditors, and regulators are asking tougher questions. They want evidence. They want consistency. Most importantly, they want to understand whether the numbers they are being shown can be trusted.

Sustainability is becoming a due diligence issue

The introduction of CSRD is accelerating a shift that was already underway.

Sustainability information is becoming more standardised, more transparent, and more closely examined. Companies are increasingly expected to produce information that can withstand external assurance, much like financial reporting.

This changes the conversation.

It is no longer enough to say energy consumption has improved. You need to show how you measured it, where the data came from, and whether someone else could verify the result.

Why energy data matters

For many organisations, energy sits at the centre of operational risk, carbon reduction plans, and future investment decisions. Investors understand this.

Energy performance influences operating costs. It affects exposure to future regulation. It impacts carbon reporting. It can even influence the credibility of wider sustainability commitments.

As a result, organisations are increasingly being asked to provide evidence rather than estimates. Not because investors suddenly care about meter readings. Because they care about risk.

Auditors are changing expectations

The major accounting firms are investing heavily in sustainability assurance services. At the same time, regulators are making it clear that sustainability information must become more reliable, consistent, and auditable.

Research from IMD examining some of the first CSRD reports found that organisations are being held to a more consistent standard, making sustainability disclosures easier to compare and scrutinise. As a result, sustainability reporting is moving out of the communications function and into the boardroom.

The Dutch Authority for the Financial Markets (AFM) has explicitly stated that CSRD assurance exists to support reliable and consistent sustainability reporting so investors can make informed decisions. 

Boards, audit committees, investors, and lenders are all asking variations of the same question. Can we trust the data?

From reporting to proof

This is why energy reporting is evolving into something much closer to energy accounting.

Not simply recording consumption, but creating a structured, traceable, and auditable record of performance. The organisations that will be best positioned for future investment will not necessarily be those making the biggest promises.

They will be the organisations that can prove what is actually happening. Because increasingly, investors are asking the same question as auditors.

"Can you show me the evidence?"

Read more >

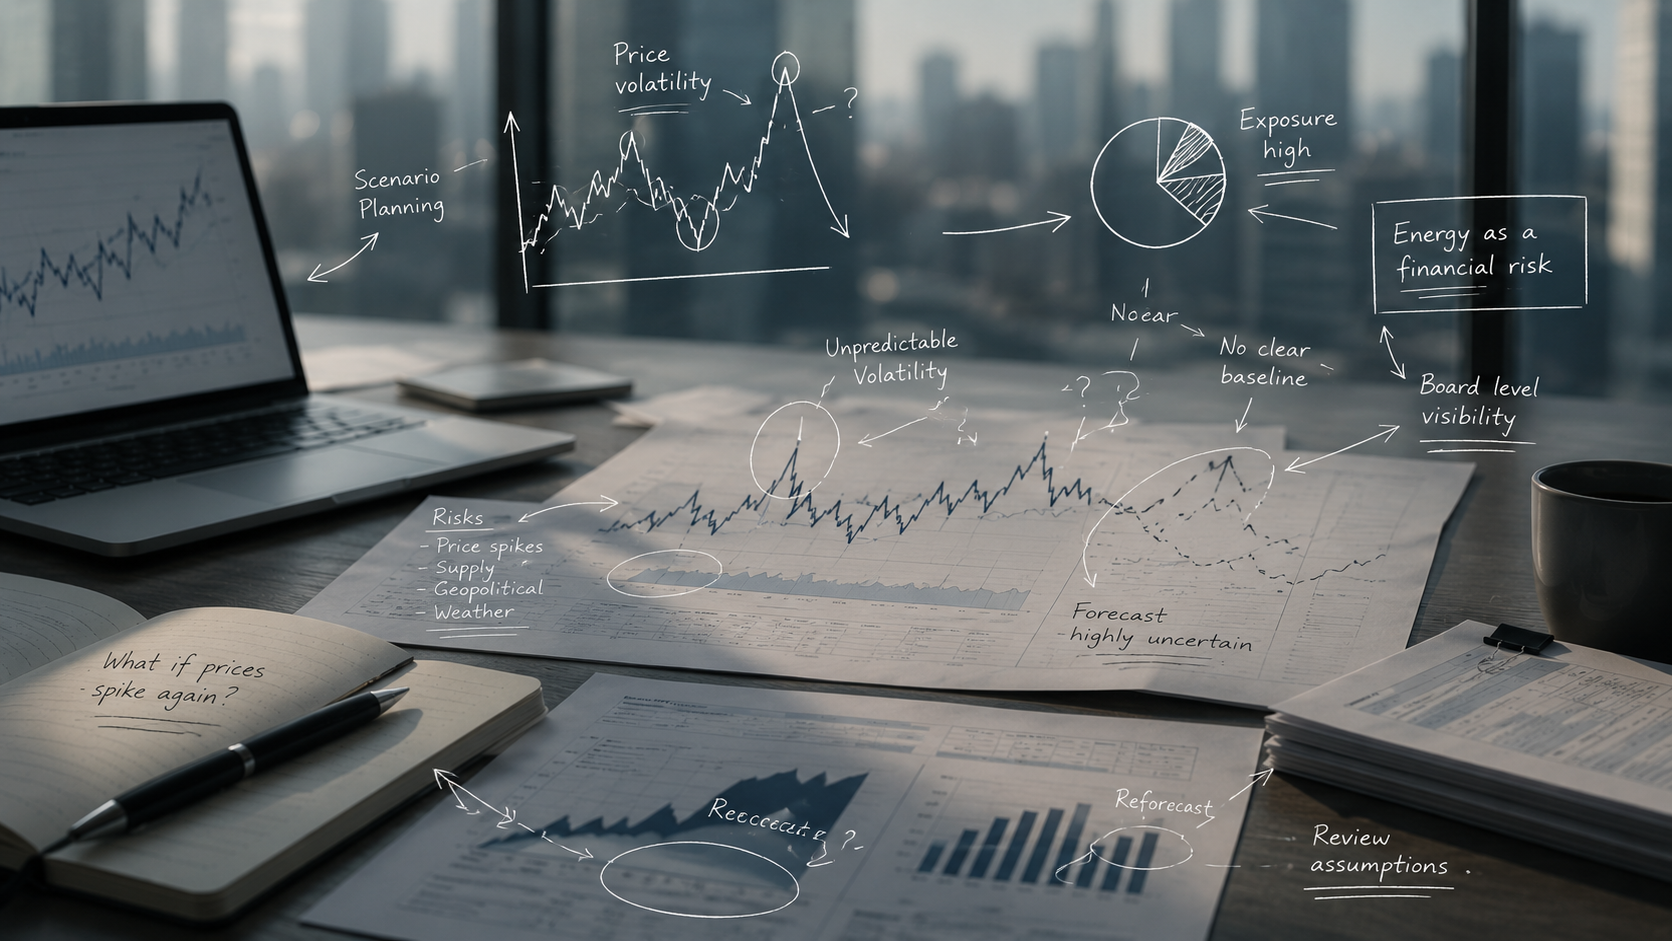
Energy price volatility is now a financial risk

Energy prices don’t just fluctuate anymore, they move in ways that are hard to predict and even harder to plan for. Energy price volatility is now a financial risk.

For a long time, energy was treated as a cost you could manage, negotiate a contract, improve efficiency, and move on. That only works when prices are relatively stable.

That stability is gone.

The market has changed

Across Europe, energy prices now shift quickly, driven by supply issues, geopolitical tension, and the growing reliance on renewables that depend on weather conditions. 

There are still calmer periods, but they sit within a wider pattern of disruption. Prices can rise sharply, then drop again, often without much warning. Electricity prices in the EU increased more than fourfold in a short period and remain vulnerable to geopolitical shocks, even after stabilising. 

This is not a temporary phase, it is how the market behaves now.

Why this hits financial performance

When prices move like this, energy stops being a predictable cost. It starts affecting forecasts, margins, and investment decisions. What looked manageable at the start of the year can shift quickly, making budgets unreliable and long-term planning harder.

Energy is no longer just something operations deal with, it directly affects financial outcomes. The focus is usually on market prices, but the bigger issue is often internal.

Many organisations don’t have a clear view of how energy is actually used. Demand patterns are unclear, inefficiencies are hidden, and cost drivers are not well understood.

That makes it difficult to respond when prices change, because there is no solid baseline to work from.

Why this is becoming a board-level issue

This is where the shift happens. Energy volatility now affects financial planning, risk management, and overall performance, which means it can’t sit in the background anymore.

It needs to be understood at leadership level, in the same way as any other financial risk. You can’t control the market. But you can control how exposed you are to it.

That starts with understanding how energy behaves inside your organisation, not just what you pay for it, but what is driving it. Without that, you are reacting. With it, you can plan.

Volatility is not going away. The real risk is not being able to deal with it.

Energy has moved from a commodity cost to a critical resource that needs to be managed, understood, and accounted for, just like any other financial driver.

Read more >

Managing energy like finance is no longer optional

Most organisations manage their finances with discipline. They track performance, understand trends, question anomalies, and make decisions based on clear data.

Energy is rarely treated the same way.

It is still seen as a cost to reduce, rather than something to manage properly. That gap is where risk starts to build. 

Energy lacks the structure finance depends on

Finance is structured. There are clear baselines, regular reporting, and a shared understanding of what good looks like. Energy is often the opposite.

Data is fragmented, reporting is inconsistent, and performance is not always clear. Decisions get made based on partial information, or not made at all. 

What financial discipline looks like in energy

When energy is managed like finance, a few things change. There is a clear view of how demand behaves over time, not just total consumption, but patterns, peaks, and variation. Performance is tracked consistently, so changes can be explained, not guessed.

There is also accountability. When something shifts, it is noticed. When performance drops, it is understood. When improvements are made, they are validated.

That level of control is standard in finance. It is still rare in energy.

Why this matters now

Energy has become less predictable and more expensive, but the bigger issue is uncertainty. If you cannot explain what is driving energy use, you cannot forecast it. If you cannot forecast it, you cannot manage financial exposure.

This is why energy is moving into financial conversations, because it behaves like a financial variable. 

Many organisations invest in upgrades or new systems, expecting improvement to follow. But without proper tracking, there is no clear link between action and outcome.

Costs may change, but the reason is unclear. Savings are assumed, but not proven. Risk remains, even if it is less visible.

From cost reduction to financial control

Managing energy like finance is not about cutting costs. It is about understanding what is happening, why it is happening, and what needs to change. That requires consistent data, clear baselines, and the ability to track performance over time.

It also requires energy to be part of decision-making at a higher level, not just something handled in the background. 

Energy is becoming part of financial planning, risk management, and reporting. Organisations that treat it that way gain clarity and control. They can respond to change, justify decisions, and reduce uncertainty.

Those that do not, remain reactive, dealing with the impact rather than managing it. The question is not whether energy should be managed like finance. It already behaves that way. The question is whether it is being treated that way inside the organisation.

Read more >